
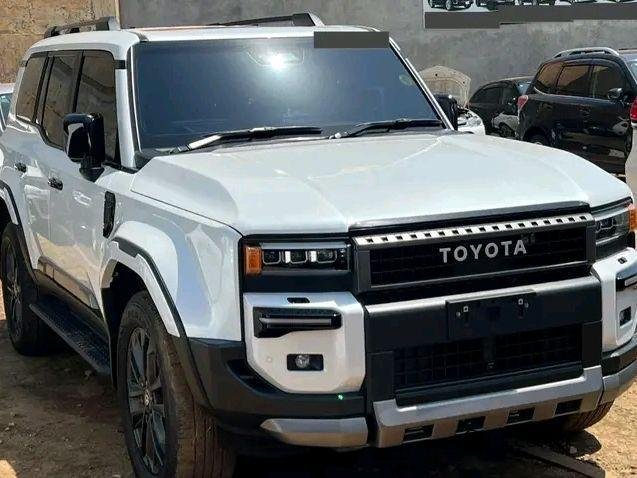
A business owner eyeing a Shs500 million luxury SUV faces a question that goes beyond price: should the company buy it, and will the taxman help foot the bill?
Company ownership can bring genuine tax advantages, especially where a vehicle helps earn business income. But under Ugandan law, the outcome depends on three separate matters: the depreciation allowed on the purchase, the deductibility of running costs, and the tax on any private benefit enjoyed by the user.
An expense paid by a company is not automatically deductible, and an asset in a company’s name does not automatically qualify for every relief.
Depreciation capped at Shs60m
Under Section 27(11) of the Income Tax Act, the cost used to calculate depreciation on a road vehicle that is not a commercial vehicle is generally capped at Shs60 million.
The law defines commercial vehicles by their load or passenger capacity, and includes vehicles used in transport or vehicle-hire businesses. How a particular vehicle is classified therefore matters.
For a Shs500 million passenger SUV, the company cannot base its claim on the full price. Assuming the 20 per cent reducing-balance rate applies, the first-year deduction on the Shs60 million cost base is Shs12 million.
At the 30 per cent corporate tax rate, and if the company has enough taxable profit, that cuts its tax bill by Shs3.6 million. The company does not receive Shs12 million back from the Uganda Revenue Authority (URA); it simply deducts that amount before its tax is calculated.
The Shs3.6 million is illustrative, not guaranteed. The rate, the vehicle’s classification and the company’s profits must all be confirmed.
The law also treats the portion of cost above the ceiling separately, including when the vehicle is eventually sold. The tax picture should therefore be assessed over the whole period of ownership, not only the first year.
Private use is taxed
A company car can serve the business and still benefit its user personally.
Where an employer provides a vehicle for private use, the value of that benefit forms part of the employee’s taxable employment income. Directorship counts as employment for this purpose.
The benefit is worked out by a formula: 20 per cent of the car’s market value when first provided for private use, multiplied by the share of the year it was available for such use, less anything the employee pays. The market value is adjusted in later years by depreciating it at 35 per cent annually on a reducing-balance basis, as specified by the Fifth Schedule for employment benefits, rather than the standard statutory depreciation rate.
If a Shs500 million vehicle is available for private use all year and the employee pays nothing, the formula gives a benefit of Shs100 million, before any later-year adjustment.
That is not the tax payable. It is the amount added to the employee’s taxable income, and the actual tax depends on total income and the applicable personal tax rates. The employer must also meet its payroll withholding and reporting obligations.
Owner-directors should not assume private use escapes tax because the car is registered as a company asset.
VAT recovery largely barred
It is a common belief that VAT on a company car can be claimed back. For passenger cars, that is generally not the case.
Section 28(6)(a) of the VAT Act restricts input tax credits on passenger automobiles, including their repair, maintenance and spare parts. The exception applies where the vehicle is acquired exclusively for a continuous and regular business of selling, dealing in or hiring passenger automobiles.
A company that uses an SUV for client meetings, for example, should not assume it can recover the VAT. Where the restriction applies, the VAT becomes part of the cost of buying or maintaining the car.
Import taxes are a separate matter. Registering a vehicle in a company’s name does not exempt it from customs duties or other import charges.
Confirming the VAT position before signing a sales or import agreement can prevent a costly budgeting error.
Fuel, repairs and insurance
Running costs are a separate question from depreciation. Section 22 of the Income Tax Act allows deductions for expenditure incurred in producing taxable income, subject to the Act’s restrictions.
Fuel for a client visit, servicing to keep a business vehicle on the road, and insurance linked to business operations may qualify. Costs for personal use do not become deductible because the company paid the supplier.
If a director takes the vehicle on a family holiday, the company must separate the private element from genuine business expenditure.
Companies should keep invoices, fuel receipts, service records, insurance documents and a log of business trips. These help support claims in the event of a URA review.
Payment by the company, ownership by the company and tax deductibility are three different things.
The cost of tying up Shs500m
There is also the commercial cost of locking up capital in a car.
The same Shs500 million could finance stock, equipment, expansion or working capital. As an illustration, a hypothetical return of 15 per cent a year would yield Shs75 million in gross returns. That is not a prediction, and all investments carry risk.
Vehicles also lose value. A car bought for Shs500 million and sold four years later for Shs350 million has lost Shs150 million. The tax consequences of that sale cannot be read from the difference alone; they depend on the depreciation history, the treatment of the cost above the ceiling and the disposal rules.
A deduction can reduce the effective cost of owning a car, but it does not remove the expense.
Before you buy
Owners should ask a qualified Ugandan tax adviser to compare buying personally and buying through the company, using the same assumptions about the car, its use and the period of ownership.
For the company option, the adviser should establish:
- the vehicle’s correct tax classification and allowable depreciation;
- whether running costs are deductible, and whether private use must be apportioned;
- whether any input VAT can be recovered under the exception;
- whether private use creates a taxable benefit and withholding duties;
- the tax treatment when the vehicle is sold; and
- whether the company has enough taxable profit to use the deductions.
For personal ownership, the comparison should cover how the purchase would be funded, the tax treatment of any company payments or reimbursements, and the costs the individual would bear directly.
The aim is to compare the total after-tax cost of each option, not the price tag or a single deduction.
Bottom line
Registering a luxury SUV under a company can make commercial sense, but the tax benefit must be proved under Uganda’s actual rules.
Depreciation on a passenger car is capped, VAT recovery is generally unavailable outside a narrow exception, and private use can create a separate taxable benefit.
The right choice depends on the vehicle’s classification, the company’s activities, the extent of private use, its taxable profits and the tax on eventual sale.
The tax efficient option is not necessarily the one that puts the car in the company’s name. It is the one with the lowest defensible after-tax cost that complies with the law.
