
A cyber incident, customer complaint or social media rumour can put a bank’s reputation under pressure within minutes, increasing the need for communication teams that can respond quickly, consistently and strategically.
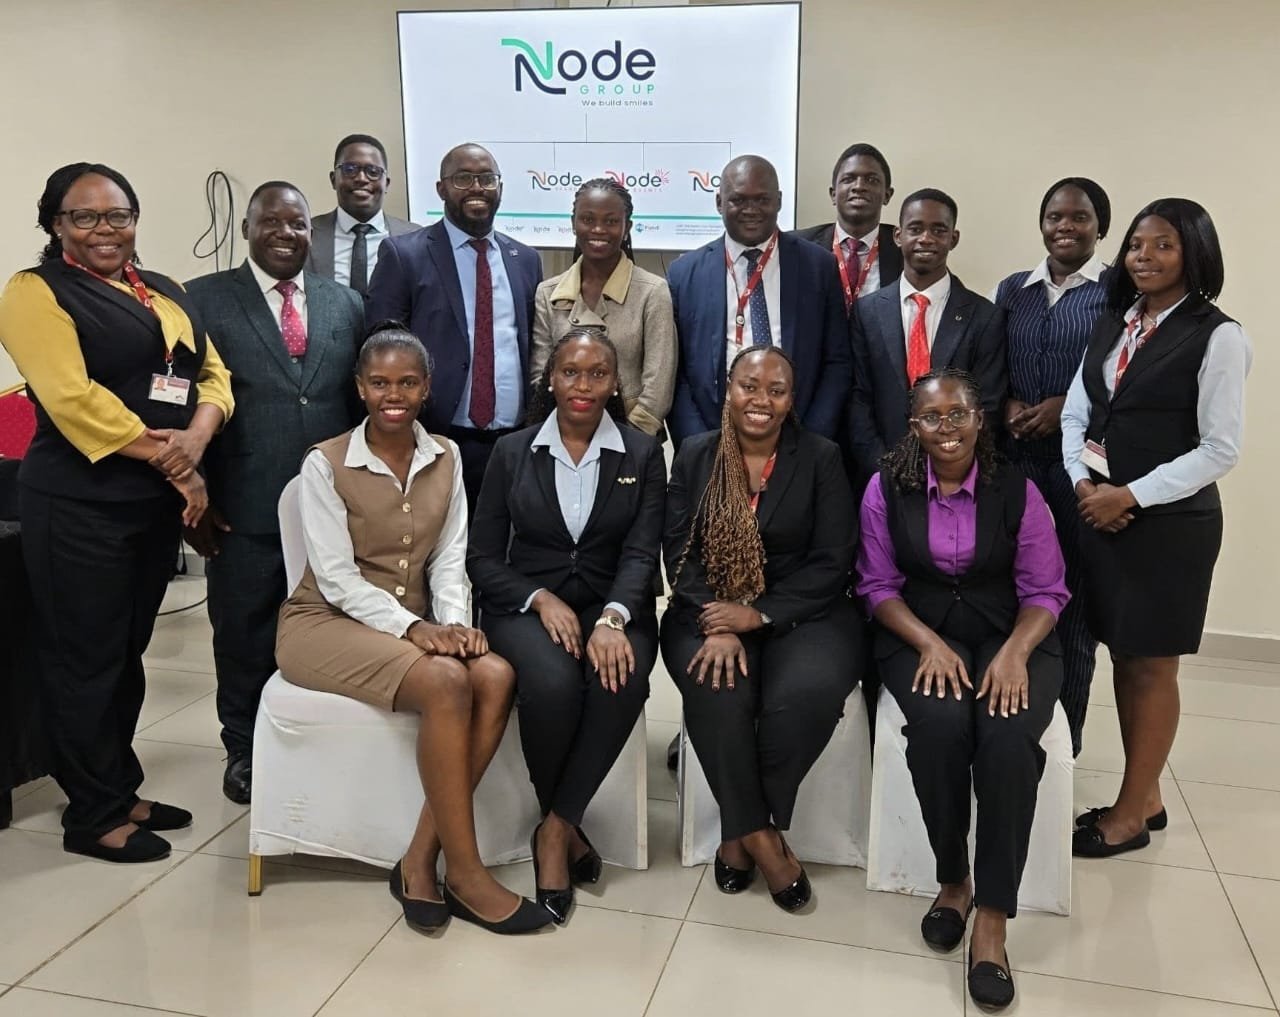
This changing communications environment is pushing financial institutions to invest more deliberately in public relations capacity, with Equity Bank Uganda recently strengthening the skills of its communications staff through a one-day strategic public relations training. Held on Thursday, September 10, 2026, the training was facilitated by Ian Rumanyika, lead facilitator at Node Group Consult, and focused on internal and external communication as well as crisis communication management.
The programme was designed to equip selected Equity Bank staff with practical skills for communicating with colleagues, customers, media and other stakeholders while responding appropriately to situations that could affect the bank’s reputation.
Rather than relying heavily on classroom theory, the training adopted a 70/30 practical learning approach, with no more than 30 percent of the programme dedicated to presentations and theory. The rest of the session focused on discussions, role plays, case studies, group exercises and realistic banking-sector scenarios.
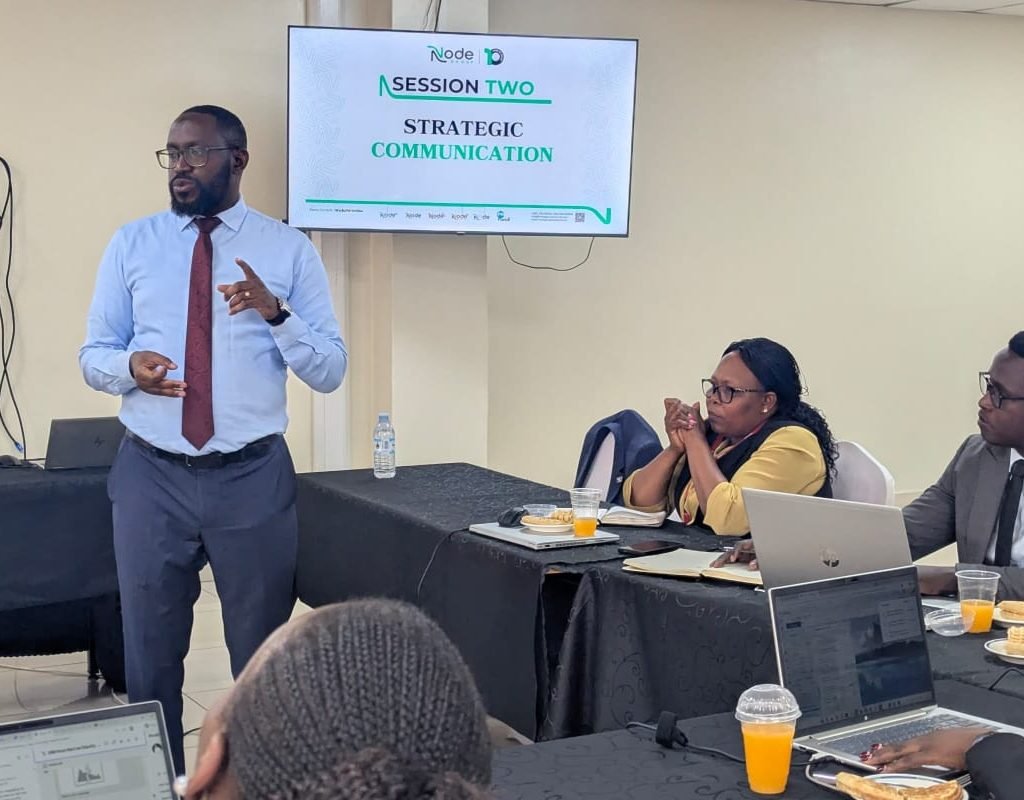
According to the training design, the approach was intended to help participants apply communication principles to situations they could encounter in their day-to-day roles, particularly when dealing with high-pressure or sensitive issues.
The training covered effective internal communication, external communication and stakeholder engagement, crisis communication, crisis response and message management. Participants examined how information flows within an organisation, the importance of clarity and feedback, and how internal communication can influence the quality of communication delivered to customers and external stakeholders.
The programme also addressed customer communication, media engagement and stakeholder expectations, with participants exploring how organisations can maintain consistent messaging when facing difficult questions or heightened public attention.
Crisis communication formed a major part of the programme. Participants were taken through ways of identifying communication risks, understanding different types of crises and coordinating responses when an issue threatens an organisation’s reputation. They also worked through crisis-response scenarios involving customer complaints, negative media coverage, social media escalation, service disruptions, misinformation and sensitive stakeholder concerns.
The practical exercises were designed to mirror the speed and complexity of real communication challenges in the financial sector. One of the central ideas behind the programme was that internal, external and crisis communication should not be treated as separate functions.
Participants examined how weak internal coordination can affect external messaging and how an issue that begins as a communication problem can develop into a broader reputational challenge if it is not addressed effectively.
The programme also placed emphasis on digital communication, where information can spread across platforms such as WhatsApp, X, Facebook and TikTok before an organisation has issued a formal response.
For financial institutions, the speed of these conversations can be particularly significant because public confidence is closely linked to how customers perceive the safety, reliability and responsiveness of a bank.
The training therefore focused not only on what communicators should say during difficult situations, but also on how they should coordinate internally, identify key messages, engage stakeholders and respond to difficult questions. The programme concluded with a crisis communication simulation in which participants responded to a realistic banking-sector reputational scenario.
They were required to apply the principles covered during the day before reflecting on the decisions they made and identifying practical actions they could take in their respective roles. The training also encouraged participants to view public relations as part of the wider responsibility of protecting organisational reputation rather than simply generating publicity.
For Equity Bank, the focus on both everyday communication and crisis preparedness reflects the growing complexity of stakeholder engagement in a financial environment increasingly shaped by digital platforms.
As banking services become more digital and customers expect faster responses, communication teams are increasingly required to work across internal departments, customers, media, regulators and other stakeholders while maintaining consistency. For communicators, this means the role extends beyond writing statements or managing media coverage.
It increasingly involves anticipating communication risks, coordinating information, supporting leadership during difficult situations and helping organisations maintain stakeholder confidence when circumstances change rapidly.
The Equity Bank training ultimately placed emphasis on turning communication knowledge into practical action, with participants expected to identify what they could do differently in their roles to improve communication and contribute to protecting the bank’s reputation.
